Record-breaking contracts, criminal charges, and an auditor who resigned. Can SMCI even be trusted?

$40 billion in annual server revenue, a massive backlog of AI orders—and at the same time, criminal charges, a revolving door of auditors, and a wave of lawsuits from investors. Super Micro Computer Inc. is the most turbulent stock in the entire AI boom.
A company that rode the AI wave—and then began to sink under its own problems
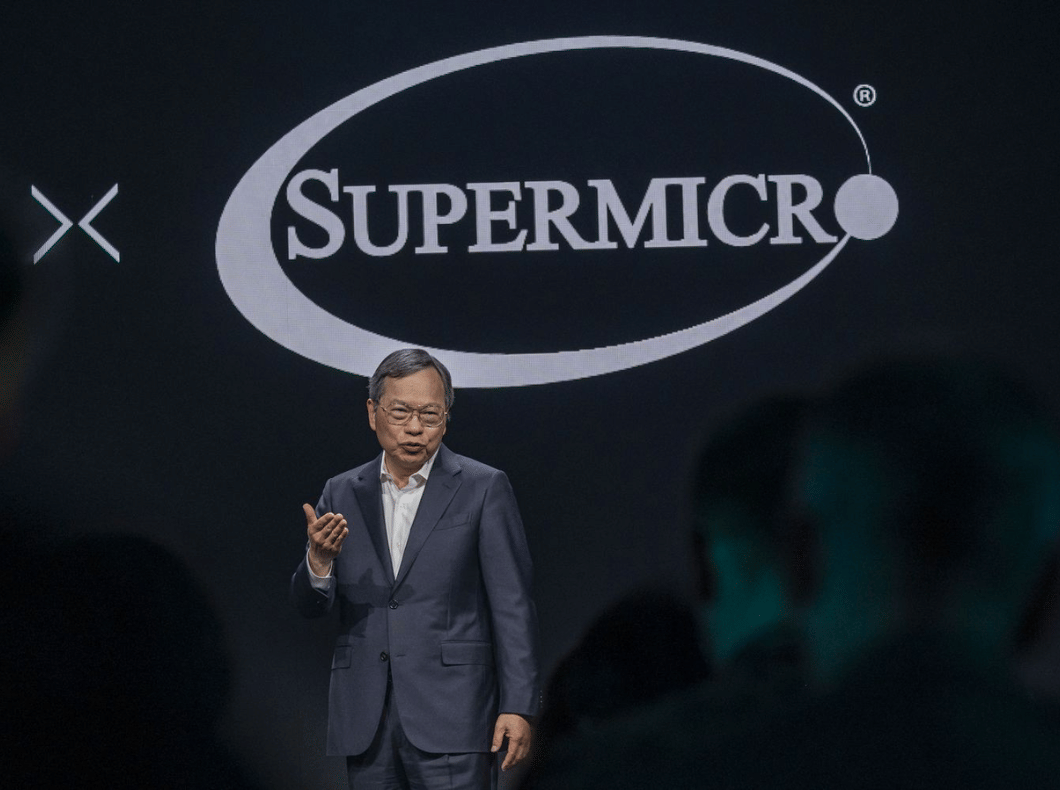
If there were a stock that best captures the paradoxes of the current AI boom, it would be Super Micro Computer $SMCI. The San Jose-based company manufactures high-performance servers and data storage —exactly what every hyperscale company building AI infrastructure needs today. Revenue exceeded $20 billion last year and, according to the company’s own guidance, is expected to reach as much as $40.4 billion this year.
And yet, since its peak in March 2024—when it traded above $100—the stock now stands at around $27. That’s a drop of approximately 75%, despite the fact that the company is growing at a triple-digit rate.
A Timeline of Troubles: From the SEC to the U.S. Department of Justice
SMCI’s problems are nothing new. In 2020, the company paid a $17.5 million fine to the SEC for inadequate internal accounting controls—and that was just the beginning.
In August 2024, short-seller Hindenburg Research released a comprehensive report in which it labeled the company a “serial repeat offender.” Hindenburg claimed that its three-month investigation had uncovered serious accounting irregularities, hidden transactions with related parties, and violations of export controls. The day after the report was published, SMCI announced a delay in its annual report—and its stock plummeted by more than 25%.
Then came a blow that is truly exceptional in the investment world: in October 2024, the auditor Ernst & Young resigned after refusing to continue participating in the financial statements prepared by the company’s management. BDO took over, and the company eventually filed its annual report —without restating past figures, but with a negative assessment of its internal controls.
The most serious development came in March 2026. The U.S. Department of Justice filed charges against three individuals associated with SMCI—including the company’s co-founder —for organizing a scheme to ship approximately $2.5 billion worth of servers equipped with Nvidia GPUs to China without licenses.
"Super Micro Computer is neither a defendant nor the target of the grand jury investigation."
SMCI Management, Q3 FY2026 Earnings Call
The company is distancing itself from the scandal and has launched an internal investigation led by independent board members, forensic accountants, and external legal counsel. Whether this will be enough to restore investor confidence remains to be seen.
Numbers That Would Normally Excite Investors
Ironically, if you set aside the legal issues, SMCI’s financial results are impressive in their own right.
In the third quarter of fiscal year 2026, revenue reached $10.24 billion —a 123% increase year-over-year. Non-GAAP earnings per share of $0.84 significantly exceeded market estimates of around $0.62.
Management raised its full-year fiscal 2026 outlook to a range of $38.9 billion to $40.4 billion, with the company holding a backlog of AI server orders worth over $39 billion. Over 80% of revenue comes from $NVDA GPU platforms —SMCI is, in effect, one of the main gateways for AI hardware.
Margins remain a weakness. The gross margin in the third quarter of fiscal 2026 reached 10.1% —significantly below the roughly 15% the company reported two years ago. Price pressure, high shipping costs, component shortages, and tariffs are all playing a role.
Customer concentration is also a concern. Two customers combined accounted for over 37% of revenue —a single data hyperscaler alone generates 27% of the company’s revenue. Losing such a customer would have an immediate and painful impact.
An Additional $7 Billion in Dilution: A Capital Plan the Market Didn’t Need
SMCI added a new problem to its list in June 2026. The company announced its intention to raise up to $7 billion through the issuance of shares and convertible instruments—the capital is intended to finance components for a record order backlog.
The market reacted with a drop of approximately 10%. Dilution on this scale will inevitably affect the value of existing shares, and that is precisely what upset nervous investors.
The company’s total debt has exceeded $8 billion, and its operating cash flow is negative —a combination that does not inspire confidence in an environment of higher interest rates and legal uncertainty.
"The company is growing at an extraordinary pace, but its story is currently compromised by the ongoing investigation and questions surrounding corporate governance."
Barclays, research report, price target cut, June 2026
Valuation: Cheap Only on Paper?
At first glance, $SMCI appears to be a cheap stock. The P/E ratio hovers around 17, and the forward P/E has even fallen below 11—which is well below the company’s historical averages and those of most of its competitors.
Analysts, however, remain cautious. The consensus among 18 S&P Global analysts is “Hold,” with an average price target of $37.63. The range of estimates is extremely wide—from $15 to $58.Such a wide spread is not a technical issue on the part ofthe analysts —it reflects the real uncertainty surrounding the company’s future.
A company with a P/E ratio of 11 based on future earnings looks attractive —but if the DOJ investigation were to ultimately target the company itself rather than just the individuals named,the entire calculation would change.
SMCI is currently banking on the fact that AI demand is strong enough to outweigh the reputational and legal risks. So far, this has more or less worked—revenue is growing. But investors know they aren’t just paying for today’s revenue. They’re also paying for management’s credibility, audit stability, and the integrity of leadership. And that’s precisely where SMCI owes an explanation.